

Fighting Financial Fraud with a Real-Time Data Platform white paper ที่จำเป็น สปอตไลท์ latest trends ใน financial fraud บริษัทต่อสู้ได้อย่างมีประสิทธิภาพอย่างไร และ Redis ช่วยธุรกิจบรรลุเป้าหมายเหล่านี้อย่างไร ดาวน์โหลดฟรีด้านล่าง
ระบาดของฉ้อโกงเป็นเรื่องจริง และสถาบันการเงินกำลังต่อสู้อย่างหนักกับการโจมตีต่อเนื่องและ Taktik ที่เปลี่ยนแปลงของ cybercriminals 隨著 global financial services landscape 演变, fraudsters เคลื่อนไหวไปพร้อมกับ digital banking transformations หาวิธีใหม่ๆ ขโมยหรือปลอม identity ของลูกค้า และทำฉ้อโกง
ตั้งแต่ pandemic ราว 35% ของ retail banking customers เพิ่มการใช้ online banking (Deloitte, 2020) สร้าง quantum leap ในการ採用 อีกประมาณ 53% ของประชากรโลกคาดว่าจะใช้ digital banking ภายในปี 2026 (Juniper Green, 2021)
เมื่อผู้บริโภคย้ายมา digital banking online fraud เพิ่มขึ้น และสถานการณ์แย่ลง Surveys เร็วๆ นี้ highlight ว่า 47% ของ businesses ประสบ fraud ใน 2-3 ปีที่ผ่านมา (PwC, 2020) ขโมยไปประมาณ $42 billion
ธนาคารและ payment processors ทำงานหนัก detect fraud ก่อนเกิด แต่ต่อสู้ไม่ทันกับ Taktik ที่ evolves ของ criminals เพราะยังคงพึ่งพา static knowledge-based identity validation, rules-based systems, รวมถึง slow, siloed systems ที่ทำให้ fraud เกิดขึ้นผ่าน channel หนึ่งโดยไม่เชื่อมต่อกับ channels อื่น
Rules-only systems detect simple, non-changing, known patterns ได้ดี เช่น validate black lists หรือ user purchase profile histories แต่ struggle ในการแยก risk จาก normal behavior
Identity theft, account takeovers, และความแข็งแกร่งของ legacy systems ทำให้ไม่สามารถ adapt กับ evolving real-world scenarios ได้ ธนาคารและสถาบันการเงินต้อง leverage digital identities และ transition ไป multilayer approach ที่จะ enhance rules-based fraud detection systems โดยเพิ่ม complementary mechanisms เช่น AI/ML transaction risk scoring, statistical analysis, และ anomaly detection
Machine learning (ML) algorithms และ artificial intelligence (AI) predictive models สามารถ evolve และ learn ได้ขณะ analyze และ detect fraud จาก historical และ real-time transactional information อย่างไรก็ตาม เนื่องจากขนาดและความซับซ้อนของ data pipelines การ implement AI/ML ที่สำเร็จ ขึ้นอยู่ไม่แค่ accurate models แต่ยัง performance และ resiliency ของ surrounding data infrastructure
Transaction Fraud
การเปลี่ยนผ่านมาสู่ online banking อย่างรวดเร็วนำไปสู่ surge ใน online fraud ทุกประเภท Studies เร็วๆ นี้ underline ความรุนแรง: 33% ของ fraud costs ของ U.S banks ในปี 2021 มาจาก online banking – เพิ่ม 26% จาก 2020 (ABA Banking Journal, 2022)
ไตรมาสแรก 2021 online banking คิดเป็น 96% ของ all banking transactions ซึ่งคิดเป็น 93% ของ fraud attempts (Security, 2021)
Financial services organizations หลายแห่งหันไปใช้ ML และ AI technology ต่อสู้ fraud และเสริม data security AI/ML models ใช้ sophisticated mathematical และ statistical algorithms เพื่อ exploit patterns และ derived inferences ระบุ risks และกำหนด rank order และ score ความน่าจะเป็น relative ที่ specified outcome จะเกิดขึ้น อัลกอริทึมเหล่านี้ใช้ analyze individual components ของ transaction และกำหนด probability ว่า unauthorized, fraudulent, หรือมาจาก stolen credit card
AI/ML model algorithms เรียนรู้ทุก iteration โดยเก็บ inferences จาก prior transactions ซึ่งเวลาผ่านไป ปรับปรุง accuracy ของ risk assessment และ scoring สามารถ adapt กับ changing biometric behavior และ transaction patterns เพื่อ handle new fraud scenarios
ใช้ AI/ML สถาบันการเงิน leverage automated transaction scoring system เพื่อ predict transactions, adjust credit scores, และ detect fraud ด้วย hyper-efficiency Real-time transaction scoring algorithms พิจารณา transaction details, user profiles, behavioral biometrics, geolocation, IP/device metadata, financial information ของ user และอื่นๆ
อย่างไรก็ตาม effectiveness ของ AI/ML models ขึ้นอยู่กับความเร็วที่เข้าถึง transaction data ได้ Machine-learning algorithms ทำ predictions จาก combination ของ data จาก offline และ online feature stores – ทั้งคู่เล่นบทบาทสำคัญใน data pipeline architecture
Offline feature stores สำหรับ fraud detection systems มี historical data เช่น ว่าแต่ละ user interact กับ bank account อย่างไร แต่ละ transaction ของ user จะแยกเป็น features หลายร้อย เพื่อสร้าง personal log ของพฤติกรรมปกติของบุคคลนั้น log นี้รวม essential data เช่น frequency ของ similar transactions, requested amount, IP address ของ location
Patterns จะถูก identify และ digital profile จะถูกสร้าง เพื่อ represent ว่าแต่ละ user interact กับ account อย่างไร แต่เป็น static data และ update เป็นระยะ ทำให้ไม่เพียงพอสำหรับ ML models ทำนาย fraud บน transactions ที่เกิดขึ้น real-time
นี่คือที่ online feature stores เข้ามาเล่นบทบาท เมื่อ user ทำ transaction online feature store จะ gather real-time data ข้าม streaming sources ต่างๆ และเปรียบเทียบกับ historical data
Machine-learning algorithms ใช้ comparisons ระหว่าง features หลายร้อย เพื่อ determine ว่ามี inconsistencies หรือไม่ เช่น Ben อยู่สเปน และซื้อของในเยอรมนี 5 นาทีต่อมา ML algorithms จะ flag เป็น potential fraud case
แต่ efficacy ทั้งหมดของ calculations นี้ ขึ้นอยู่กับ online feature store ให้ real-time data การตัดสินใจ approve หรือ reject transaction ต้อง accurate และ instantaneous เพื่อปิดกั้น fraudulent activity
Leverage online feature store ช่วยป้องกัน fraud ข้าม payment mechanisms ต่างๆ:
- Credit และ debit card payments
- Person-to-person transfers
- Bank account credits และ debits
- Mobile wallets และ e-payments
Know Your Customer (KYC)
ธนาคารต้องปฏิบัติตาม know-your-customer (KYC) regulations มานาน และยังเป็นวิธีที่ชอบในการต่อสู้ financial fraud แต่หลายแห่งยังพึ่งพา knowledge-based authentication (KBA) data ที่ใช้เป็น static และไม่ได้ update บ่อยพอที่จะ reliable หรือ safe การรั่วไหลข้อมูลที่ Equifax และ Capital One แสดงว่า identity data ถูกขโมยและใช้ทำ fraud และ account takeovers
ธนาคารต้อง agile และมีความเร็วตัดสินใจ fast decisions ที่ dispel fraudulent activity อย่างรวดเร็ว การตัดสินใจจาก KBA criteria เช่น ชื่อ ที่อยู่ social security ให้ criminals วงโอกาส out-maneuver bank data security systems
ต้องมี sophisticated technology มากขึ้น เพื่อสร้าง powerful cybersecurity, strengthen data security systems และ mitigate risk ของ data breaches – ซึ่งเป็นเหตุผลที่ธนาคารหลายแห่งหันไป dynamic digital identities ผ่าน modern approaches นี้ document verification และ biometric records รวมกับ intricate behavioral patterns สร้าง digital identity ให้แต่ละ user
วาง padlock ที่แข็งแกร่งกว่าบน accounts ทำให้ criminals ยากขึ้นในการ fake หรือ mimic digital identities แต่ครั้งอีกครั้ง speed เป็นปัจจัยสำคัญ Digital identities complex ประกอบด้วย sources และ data types หลายอย่าง ความยากคือ update ทุกอย่างพอดีพอเพียงให้ banks อยู่หนึ่งก้าวหน้า criminals โดยไม่รบกวน user experience
ยิ่งท้าทายเพราะ criminal underworld evolves พร้อมกับ banks ค้นพบ savvier ways ทำ fraud โดยสร้าง synthetic digital identities – process ที่ blend real และ fake customer information เข้า identity ใหม่ เช่น ขโมย social security number มาสร้าง fake date of birth หรือ home address โลกการเงินรู้จัก synthetic fraud threat มาก ซึ่ง cost U.S. banks $20 billion ในปี 2020 เพียงอย่างเดียว (ABA Banking Journal, 2021)
Fraudsters รู้วิธีอยู่ undetected โดย ensure payments จ่ายทันเวลา และ build credit history เพื่อหลีกเลี่ยง risk factors ทำให้ detect synthetic fraud เกือบ impossible สำหรับ banks Best defense คือ detect ตอนสร้าง account หรือ early transaction/payment process
สำคัญเพราะ หาก criminals ได้เวลาพอ พวกเขาจะไปขั้นต่อไปของ fraud cycle โดย alter fake information สร้าง additional digital identities กล่าวคือ formulate และ create network ของ fake identities ที่สุดท้าย connected และ shared ด้วย pieces of information หนึ่งหรือมากกว่า เช่น bank accounts, phone numbers, social security numbers ฯลฯ
โอกาสสำหรับ banks detect fraudulent activity โดย identify connections ระหว่าง personal information ของ user
Solution คือใช้ graph database ที่ represent และ store data เป็น series ของ nodes และ edges ที่ model relationships ระหว่าง data points Fraud และ data security analysts จึง detect suspicious connections หรือ patterns โดย traverse graph ของ customers (digital identities) และ/หรือ transaction attributes โดย preference แบบ real-time
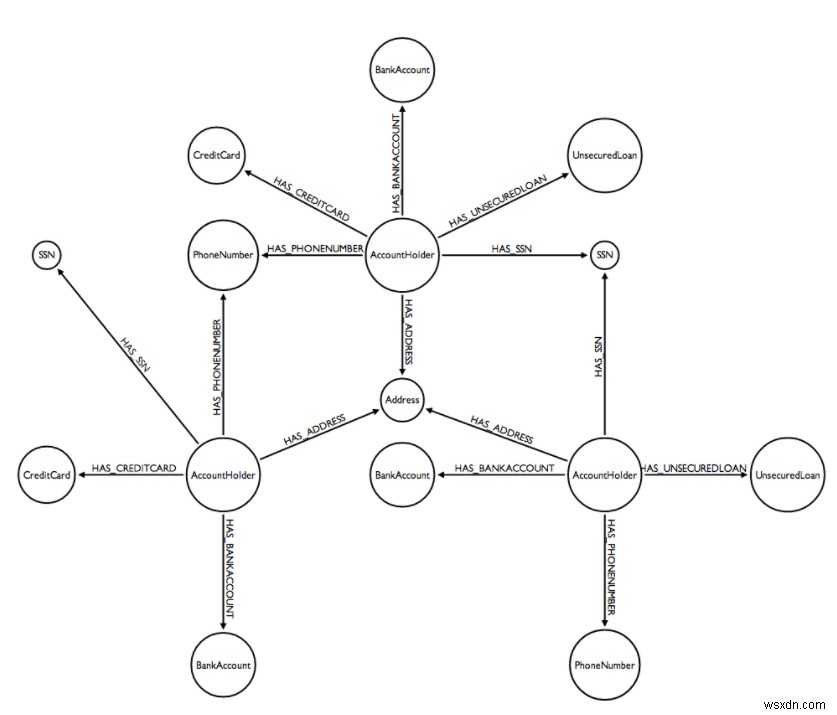
เพื่ออยู่หน้า criminals ธนาคารต้อง leverage low-latency in-memory multi-model databases ที่ deliver high throughput ที่จำเป็น เพื่อ keep digital identities updated และ build identity graphs detect synthetic fraud แบบ real-time
Real-time database นี้เร็วและยืดหยุ่นกว่า traditional relational databases และจะให้โอกาส banks identify customers ถูกต้องและ flag suspicious transactions มากที่สุด
Anti-Money Laundering (AML)
เงินก่อสร้าง (dirty money) ต้อง money laundering และธนาคารเป็น channels ที่ fraudsters ใช้สะสมทรัพย์ผิดกฎหมาย ความจริงคือ money laundering ทั่วถึงและ problematic การต่อสู้ยังคงเป็น top-tier challenge แต criminals ยังหาวิธี disrupt system
ประมาณ $2 trillion ถูกล้าง globally ทุกปี (Deloitte, 2020) และ 50% ของ money laundering ไม่ถูก detect ข้าม industry ทั้งหมด (Renolon, 2022) Governments กดดัน banks ให้ vigilant มากขึ้น และ validate transactions ด้วย AML regulations ที่ stringent มากขึ้น
AML-related fines สูงขึ้นใน السنوات gầnๆ รวมเป็น $10.4 billion ทั่วโลกสิ้นปี 2020 (Compliance Week, 2020) highlight ความล้มเหลวของ financial institutions ปฏิบัติตาม money laundering laws แต่ 62% ของ compliance officers บอกว่า criminal activity ยากต่อการ detect (Renolon, 2022) banks ต้องหาวิธีใหม่ clamp down money laundering และ strengthen cybersecurity
ธนาคารหลายแห่ง leverage AI และ digital identity technologies เพื่อ enhance transaction monitoring systems และ weed out money launderers Network analytics ช่วย identify hidden links ระหว่าง entities ที่ likely missed ผ่าน traditional methods
แต่ linchpin ของ AML compliance program ใดๆ คือ monitoring system ที่ให้ transaction scoring ข้ามหลาย variables แบบ real-time Data ที่ต้อง analyze เป็น colossal และความเร็วที่ process ทุกอย่าง 决定ว่า banks identify suspicious transactions สำเร็จแค่ไหน
ธนาคารต้องการ Real-Time Database เพื่อ Clamp Down Fraud
เราอยู่ใน fast-paced environment ที่ criminals evolved และค้นพบ savvier ways ขโมยและสร้าง fake identities ทำ fraud ธนาคารต้อง adapt สู่ digital age และออกจาก rigid และ slow legacy RDBMS systems ที่ไม่รองรับ modern AI/ML-based fraud detection และ dynamic digital identities
ผลคือ ธนาคารหลายแห่งหันไป real-time databases เพื่อ agile, responsive, และ adept ในการ tackle fraud Redis Enterprise ด้วย native modules RedisJSON, RediSearch, RedisGraph, RedisTimeSeries, และ RedisBloom ถูก leverage โดย financial services firms หลายแห่ง เนื่องจากความสามารถ process multiple data models อย่างมีประสิทธิภาพ และ identify suspicious patterns
มัน empower banks โดยให้ fraud detection platforms เข้าถึง real-time ที่จำเป็น เพื่อ analyze patterns ใน transactions อย่างรวดเร็ว และ augment KYC programs ด้วย tools ใหม่สำหรับ digital identity Redis Enterprise ให้ financial services companies mission-critical, in-memory database ด้วย sub-millisecond performance, global scalability, 99.999% uptime, multicloud support และอื่นๆ
อ่าน whitepaper นี้เพื่อค้นพบเพิ่มเติมว่า Redis Enterprise ขับเคลื่อน real-time fraud detection อย่างไร
